Deer Strikes and Auto Insurance: Why Comp Coverage Usually Applies
Hitting a deer and swerving into a guardrail can damage a car the same way and still be paid under different parts of the policy. A short guide to how animal-strike claims usually work.
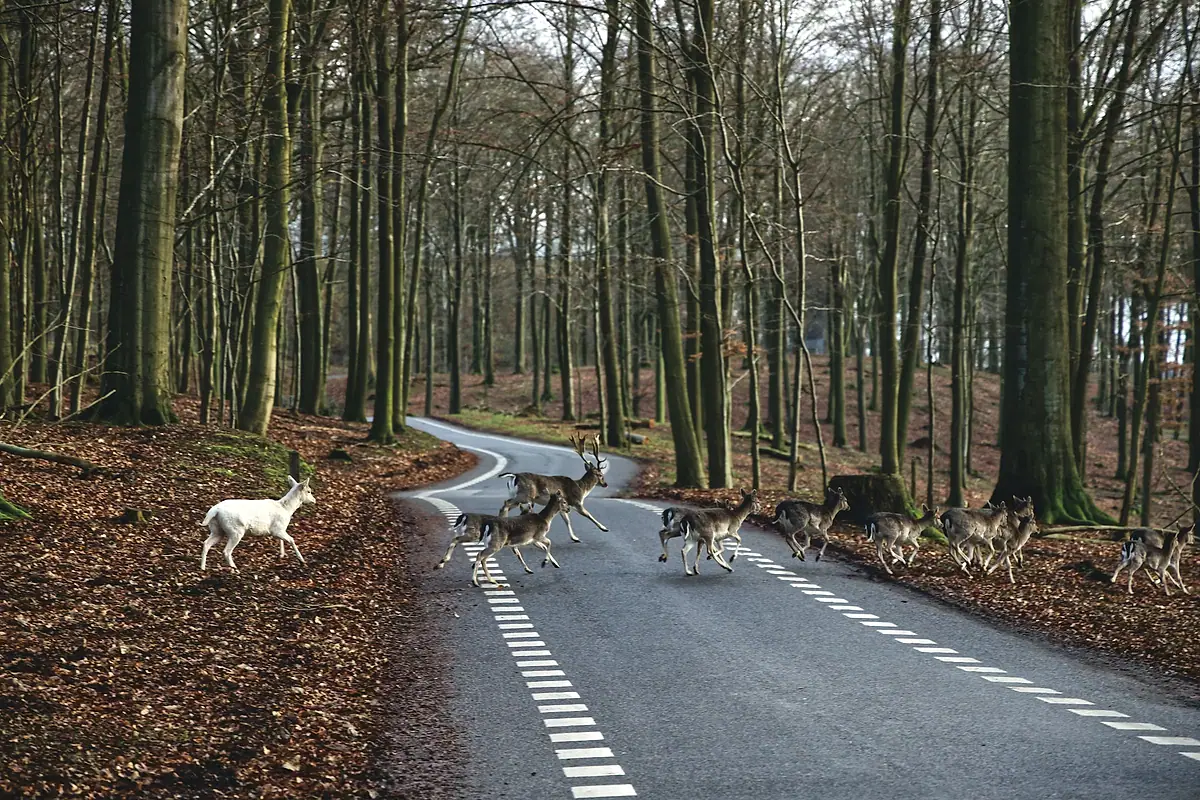
A deer strike is one of the few crashes where the coverage question is often simpler than the repair. In most standard auto policies, damage from hitting an animal is paid under comp coverage (other-than-collision), not under collision coverage. The National Association of Insurance Commissioners says so directly, and adds the catch: comp is an optional part of the policy.1
Two parts of the policy
Collision coverage pays to repair or replace your car after it hits another vehicle or an object. Comp pays for damage from causes other than a collision, such as theft, fire, flood, vandalism and, in most policies, animals.2 Insurers file a deer strike under comp even though, physically, the car collided with something. The Texas Department of Insurance lists “hitting an animal” among the losses most policies pay, provided the driver carries comp.2
The deductible still applies
A comp claim carries its own deductible, which may differ from the collision deductible on the same policy. The Texas Department of Insurance notes that drivers pay a deductible on both collision and comp claims.2 If the repair estimate is close to the deductible, filing a claim may not be worth it. The Iowa Insurance Division suggests filing when damages exceed the deductible.3
Liability-only policies
Liability coverage pays for damage you cause to other people and their property. It does not pay to fix your own car. NAIC says that a driver who has only collision or liability coverage will not be covered for damage from hitting an animal.1 The Iowa Insurance Division gives the same warning.3 Drivers who own their cars outright often drop comp and collision to save on premiums; a deer strike is when that choice shows. A lender usually requires both coverages while a car is financed.2
The swerve problem
Here is where the coverage lines matter. If you hit the deer, the claim usually goes under comp. If you swerve, miss the deer and hit a tree, a guardrail or another car, you have collided with an object, and the claim usually becomes a collision claim, with the collision deductible and, depending on the insurer, possible effects on your premium. Swerving also tends to make the crash more dangerous, which is why NAIC warns that drivers who swerve “could lose control and hit a tree or veer into oncoming traffic.”1
The difference in coverage can also tempt drivers to say they hit a deer when they did not. Virginia transportation researchers noted that some policies cover deer crashes but not crashes with fixed objects such as a guardrail or a tree, and that false deer claims would inflate insurance-based counts.4 A claim that does not match the damage invites an investigation.
Documenting the strike
NAIC advises photographing the vehicle damage, the roadway and any injuries.1 Note the time and place and get contact details for any witnesses. Fur, hair or blood on the bumper or grille supports an animal claim. If the crash involved injuries, or if state law or the insurer requires it, file a police report. Rules on reporting differ by state; Virginia’s are covered in our guide to deer collisions in Virginia.
Glass and rental cars
Glass. Windshields often crack in deer strikes. Glass damage is commonly handled under comp; the Massachusetts Division of Insurance, for one, says glass and windshield coverage in that state is provided by comp, and that glass deductibles are permitted.5 Some insurers offer separate glass terms, so check the declarations page.
Rental cars. A rental while your car is in the shop is usually a separate, optional coverage, often called rental reimbursement. The Texas Department of Insurance describes it as paying “for you to rent a car if yours is stolen or being repaired after an accident.”2 Without it, the rental may be out of pocket.
Policies and states vary
Everything above describes how standard personal auto policies commonly work. Coverage names, deductibles, glass terms and claim handling differ by insurer, by policy and by state, and endorsements can change any of them. Read your own declarations page, and ask your insurer or your state’s insurance department when something is unclear. Nothing here is legal or insurance advice about a specific claim.